Ramp
- 4.7
- Rating
- 100.00K
- Installs
- Free
- Price
 Analysis by App-foxy
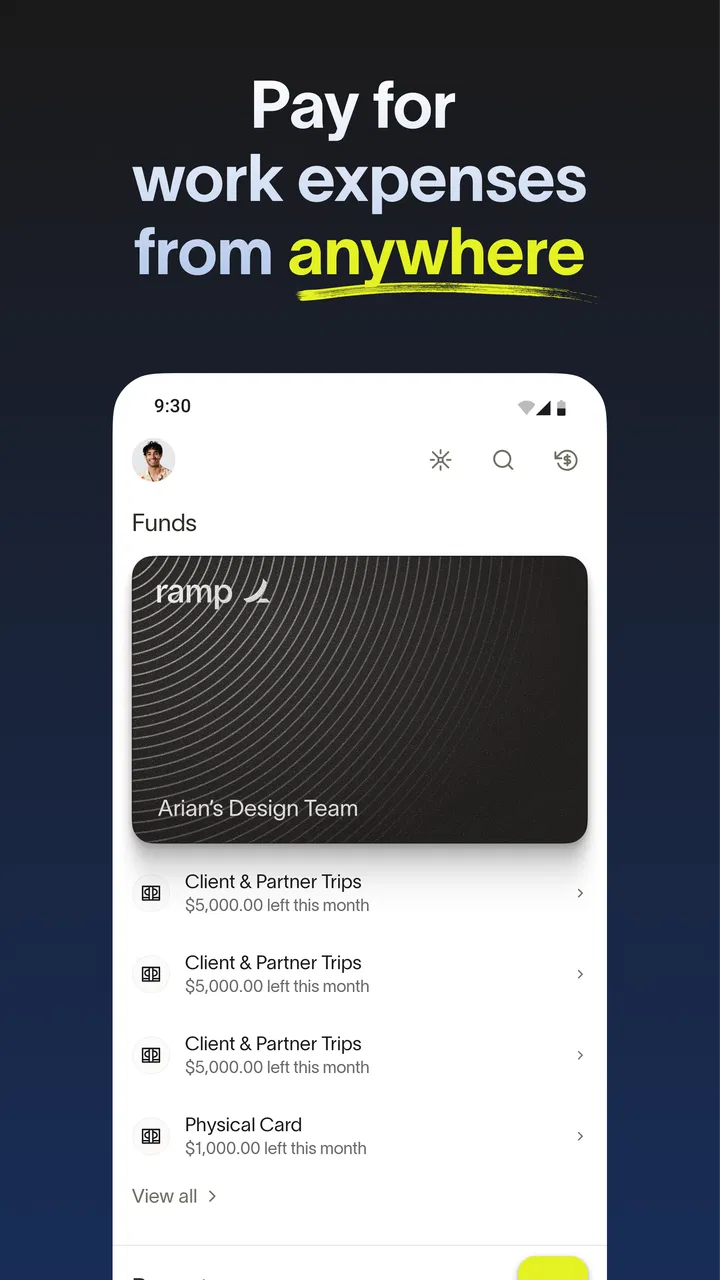
Managing business spending from a phone sounds simple until a payment needs attention while you are away from your desk, a receipt is still in your pocket, or a colleague asks for an update during a commute. That is the space where Ramp tries to be useful. I reviewed it as a finance app from Ramp Business Corporation, and my overall impression is that its value depends less on flashy presentation and more on whether your company already uses Ramp as part of its spending workflow.
The app is free to download and is rated for Everyone, which makes the first step approachable. Its average score is 4.7 from around 2.2K ratings, and it has passed 100K installs. Those figures suggest that it has found a clear audience, but they should not be mistaken for proof that it will suit every business. Ramp is built around business finance rather than personal budgeting, so the right question is not simply whether it looks convenient. The real question is whether it gives you a practical mobile connection to the financial controls your organization already relies on.
How Ramp feels when the network is part of the workflow
My first takeaway is that connectivity is central to the experience. A finance app is rarely just a static notebook. It has to reflect current business information, account activity, spending decisions, and whatever actions your organization permits. That means the useful moments are usually the moments when the phone can reach the service and return current information without making you wait at a computer.
You May Also Like

 Blood Strike: 2.5 Anniversary
Blood Strike’s Loadouts Turn Every Drop Into a Tactical Gamble
A close look at Blood Strike’s custom loadouts: how fast access to signature weapons reshapes its battle royale rhythm, rewards preparation, and narrows the gap between fights.

 Pandora - Music & Podcasts
Pandora’s Music Is Easy to Start, but Harder to Recover
Pandora’s strength is its low-effort path from a seed to a station. Its weak spot is how much confidence it asks you to place in connection, setup, and quiet recovery.

 8 Ball Pool
 Is Built on Rivalries, Rematches, and Routine
A close look at the rivalries, rematches, shared routines, and unanswered safety questions that turn a quick pool match into a persistent mobile community.

 Samsung Music
’s Quiet Strength Is Playing What You Already Own
Its reach comes less from spectacle than from dependable access to a personal library. That simplicity is both the app’s strongest retention engine and its ceiling.

 AccuWeather: Weather Radar
AccuWeather Review: A Quick, Clear Forecast for Everyday Decisions
For everyday plans, the best forecast is the one you can understand quickly. AccuWeather makes rain timing, radar, and local conditions easy to act on, with a few trade-offs.

 Hill Climb Racing
Why Hill Climb Racing Still Turns Crashes Into One More Run
A tiny car, a bumpy hill and one more upgrade: Hill Climb Racing keeps resurfacing because its simple chaos makes every near-miss feel personal.
More From Our News Desk



This matters in ordinary situations. Imagine leaving a meeting and realizing that a receipt for a business purchase is still in your jacket. If you can open Ramp while the details are fresh, the mobile workflow can help you deal with the task before it becomes part of a larger pile. The advantage is not merely that the screen is smaller than a laptop. It is that the phone is already with you at the moment when the financial detail is easiest to remember.
The same principle applies when someone needs a quick decision during travel. A manager may want to check a spending item, a team member may need to handle an administrative task, or an employee may need to review information connected with company spending. In each case, the app is most valuable when it reduces the need to postpone the task until returning to a desk.
There is also a trade-off. A network-connected finance workflow is only as responsive as the connection and the service behind it. In a strong signal area, that relationship is easy to overlook. In a basement, crowded venue, airport queue, or moving vehicle, it becomes part of the product. I would not treat Ramp as a tool to depend on blindly during a time-critical payment conversation. I would treat it as a mobile access point that works best when I give it enough time to load and verify the latest state.
That distinction is important because business finance rewards accuracy more than speed. If a screen is slow, repeatedly refreshing it may not improve the situation. My practical habit would be to pause, confirm whether the connection is stable, and avoid assuming that an action has completed simply because I tapped it. The safest mobile routine is to look for a clear change in status before moving on.
Useful on the move, but not a replacement for every desktop task
Ramp makes the most sense for short, focused interactions. I would use it when I need to check something, respond to a business-finance task, or capture information while the context is still fresh. I would be less inclined to use a phone for a long review session involving many records or complicated decision-making. A larger screen remains easier for comparing details, reading supporting information, and keeping several pieces of context visible at once.
This is one of the less obvious trade-offs of a mobile finance app: convenience can encourage rushed decisions. When a task feels easy to complete from a phone, it is tempting to approve, submit, or classify something without checking the surrounding details. My recommendation is to use the mobile app for timely handling, then reserve more involved reconciliation for a setting where you can concentrate.
That approach also helps answer a question many potential users have: is Ramp useful for an individual? In my view, it is primarily useful when you are connected to a business spending process. Someone looking for a personal expense tracker, a household budget, or a simple bank-balance viewer should look elsewhere. The app’s identity is tied to company finance, so its usefulness grows when there are shared business responsibilities rather than only one person tracking private spending.
Mobile context changes what “quick” really means
Using a finance app on a phone is not the same as using a finance app at a desk. I might be standing outside a client location, sitting in a taxi, or trying to finish an administrative task between meetings. In those situations, I value a workflow that lets me deal with one clear item at a time. I do not want to reconstruct an entire business transaction from memory while distracted.
A good mobile habit is to handle the smallest complete unit of work. If I have a receipt, I would deal with it while I remember the purpose, date, and people involved. If I am reviewing a spending item, I would check the essential context before taking action rather than treating a notification as the whole story. This is a concrete advantage of having the app available: it can shorten the gap between an event and the paperwork around it.
There is a corresponding weakness. Phones are easy to misplace, easy to interrupt, and often used in public. I would avoid opening sensitive financial information where other people can read over my shoulder, and I would not treat a quick glance as a substitute for careful review. The mobile setting is convenient, but it also demands more awareness from the user.
What happens when the connection fails
The most important connectivity test is not a perfect session. It is what I do when the connection becomes unreliable. With Ramp, I would plan for moments when a screen takes longer to load or an action needs confirmation. The sensible response is to avoid duplicate taps, record what I was trying to do, and check the app again once the connection is dependable.
This may sound cautious, but duplicate actions are especially undesirable in finance. If a button appears unresponsive, repeatedly pressing it can make it harder to know whether the request was ignored or simply delayed. I prefer a recovery routine: wait briefly, verify the connection, reopen the relevant area if necessary, and confirm the resulting status before attempting anything again.
For a receipt or expense detail, I would keep the original receipt until I can see that the information has been handled successfully. That small habit protects against the most common mobile mistake: assuming that capturing information and successfully submitting information are always the same event. They are not necessarily the same from the user’s point of view, especially when the network is unstable.
Travel makes this more important. Hotel lobbies, conference centers, public transport, and international roaming can all produce inconsistent access. I would complete urgent finance tasks before entering a known dead zone, and I would avoid leaving the only copy of a receipt or transaction detail inside a workflow that has not visibly finished. This is not a criticism unique to Ramp; it is the practical cost of using any connected finance service away from a reliable desk connection.
Another question is whether Ramp can serve as an emergency fallback when a company’s normal process is unavailable. I would be careful here. The app can be a convenient mobile route into the Ramp workflow, but it should not be treated as an independent offline ledger or a guaranteed substitute for every business-finance channel. If the organization needs a formal backup process, that process should exist separately rather than relying on a phone app to solve every outage.
Keeping data use sensible without making the app inconvenient
Finance apps do not usually need constant attention throughout the day. My preferred approach would be deliberate use: open Ramp when I have a specific task, complete that task, and close it rather than repeatedly checking it without a reason. This reduces distraction and makes it easier to notice whether the information I am viewing is current.
On a limited mobile connection, I would favor a stable Wi-Fi network for longer sessions and use mobile data for short checks when necessary. I would also avoid trying to process a large backlog while traveling unless I had a dependable connection and enough battery. A finance workflow is a poor place to discover that the phone is about to shut down or that the network has become too weak to complete a submission.
The practical tip here is to separate urgent actions from review work. A quick mobile check may be appropriate when a decision cannot wait. A detailed examination of many transactions is better handled later, with a larger display and a stronger connection. This division keeps the phone useful without forcing it to become the only place where business finance is managed.
It also clarifies who should skip the app. If your company does not use Ramp, if you only want personal money management, or if your work requires extensive spreadsheet-style analysis on a small screen, the app is unlikely to become your best solution. A conventional personal finance app may be better for household spending, while a desktop accounting platform may be more suitable for deep reconciliation and reporting.
Ramp compared with the usual finance alternatives
Compared with a personal budgeting app, Ramp is a more natural fit for business spending because the user’s needs are connected to an organization rather than only to personal financial goals. A budgeting app may be better at helping one person understand household categories and monthly habits. Ramp becomes more relevant when spending has to be handled within a company context and when mobile access matters during the working day.
Compared with a bank’s mobile app, the distinction is also meaningful. A bank app is usually centered on the account relationship with that bank: balances, transfers, and banking activity. Ramp is better considered as part of a business spending and administration workflow. I would not choose between them as if they were identical products. A bank app answers banking questions; Ramp is aimed at the business-finance tasks surrounding company spending.
Compared with desktop accounting software, the advantage is immediacy. I can imagine using Ramp when I am away from my workstation and need to deal with a task before details fade. Desktop software remains stronger for a long, structured session where I need room to compare records and investigate discrepancies. The best choice may therefore be complementary rather than exclusive: mobile handling for timely actions, desktop work for deeper control.
One of the app’s less obvious strengths is that it can support better timing. Financial administration often becomes harder because small tasks are postponed, not because each task is inherently complicated. Handling a receipt or checking a business item close to the moment it occurs can reduce memory gaps and end-of-week cleanup. That benefit depends on disciplined use, but it is more valuable than simply having another finance icon on the phone.
There is a limitation on the other side. Mobile convenience can make a business process feel more individual than it really is. Company spending often involves responsibility, context, and review, so I would not use the speed of a phone interaction as a reason to bypass internal checks. The app is most helpful when it supports a clear process, not when it encourages people to make financial decisions without enough context.
Version, access, and the practical setup decision
Ramp is currently listed at version 0.148.0 and requires at least iOS 11. That makes the device question straightforward: before committing to a mobile workflow, I would check that the phone can run the current app and that it has enough free space, battery, and dependable access for business use. Compatibility is not exciting, but it is the kind of detail that determines whether a finance tool is genuinely available when needed.
The app is free, which removes a direct download-price barrier. That does not automatically mean every business process around it is free or that every organization will use it in the same way, so I would still confirm how Ramp fits into the company’s existing arrangement before asking a whole team to rely on it. The developer is Ramp Business Corporation, and the app’s business orientation is clear enough that I would evaluate it with workplace use in mind rather than as a general-purpose money app.
If I were introducing it to a team, I would start with a small routine: use the phone for one or two common tasks, test the workflow on a reliable connection, and decide what should still be handled on a computer. I would also agree on what counts as a completed action and what to do when the network fails. Those simple rules prevent the app from becoming a source of uncertainty during busy periods.
My connectivity verdict
After looking at Ramp through the lens of mobile and network-dependent use, I see it as a practical companion for people who already operate inside a Ramp-based business finance process. Its strongest moment is the gap between “this needs attention” and “I am back at my desk.” That is where a phone can save time, preserve context, and stop small administrative jobs from accumulating.
My recommendation comes with boundaries. I would not choose it for personal budgeting, use it as an assumed offline backup, or rely on a weak connection for an important financial action without checking the result. I would also keep a larger-screen workflow available for detailed review. Those are not reasons to dismiss it; they are the conditions that make its mobile strengths realistic.
Ramp is worth considering when your business needs timely mobile access to its spending workflow, not merely another way to view money. For the right user, the free app and broad device accessibility make trying it relatively easy, while the high average rating and more than 100K installs show that it has an established mobile audience. My final advice is simple: use it intentionally, keep receipts and records until actions are confirmed, and let the quality of your connection guide whether a task belongs on the phone or at the desk.
FAQs for Ramp
01What is Ramp, and what does it do?
Ramp is a financial management app designed to help businesses automate and streamline their expense management processes. It offers features like real-time expense tracking, automated receipt matching, and detailed analytics. The app aims to save time and reduce errors by eliminating manual expense reporting and providing insights into spending patterns.
02Is Ramp suitable for small businesses?
Yes, Ramp is suitable for businesses of all sizes, including small businesses. It provides scalable solutions that can grow with your company. The app offers intuitive tools for managing expenses, setting budgets, and tracking financial performance, making it a versatile choice for startups and established enterprises alike.
03How secure is my data with Ramp?
Ramp prioritizes security with robust data protection measures. It uses encryption to safeguard sensitive information and complies with industry standards and regulations. Regular security audits and updates ensure that your data remains secure. Users can trust Ramp to handle their financial information with the highest level of confidentiality.
04Can Ramp integrate with other financial software?
Yes, Ramp offers seamless integration with various financial and accounting software, such as QuickBooks, Xero, and NetSuite. This allows businesses to sync their financial data effortlessly, ensuring a smooth flow of information across platforms and reducing the need for manual data entry.
05Does Ramp offer customer support for users?
Ramp provides comprehensive customer support to assist users with any issues or questions. Support is available through multiple channels, including email, live chat, and phone. Additionally, Ramp offers a detailed help center with articles and tutorials to help users make the most of the app's features.
Pros
- Intuitive UI for easy navigation.
- Wide variety of ramp design options.
- Real-time collaboration features.
- Seamless integration with other tools.
- Cross-platform support enhances accessibility.
Cons
- Limited offline functionality.
- Occasional syncing issues.
- Requires modern hardware for best performance.
- Some features locked behind paywall.
- Customer support response time can be slow.

Ramp
Gallery